U.S. Stock Market Monthly Review: September 2026 – Rising Yields, Fed Policy, AI Strength, and a Divided Wall Street
U.S. Stock Market Monthly Review: September 2026
September 2026 was a more complicated month for U.S. stocks than the headline index numbers suggested. The Dow Jones Industrial Average fell 4.9%, while the S&P 500 declined 0.7%. The Nasdaq Composite, however, gained 1.7%.
Behind those figures, the market was becoming increasingly divided. Large-cap technology and communication stocks remained relatively strong, while smaller companies and many other parts of the market struggled. At the same time, Treasury yields climbed sharply, the Federal Reserve raised interest rates, and oil prices increased.
The result was a market in which investors continued to pay for growth and artificial intelligence exposure while becoming more cautious about interest-rate-sensitive parts of the economy.
September at a Glance
| Index / Market Indicator | September 2026 Performance |
| Dow Jones Industrial Average | -4.9% |
| S&P 500 | -0.7% |
| Nasdaq Composite | +1.7% |
| Russell 2000 | -5.3% |
| Nasdaq-100 | +3.3% |
| 10-Year Treasury Yield | 5.29% |
| 30-Year Treasury Yield | 5.62% |
The monthly index performance shows the unusual split. According to Nasdaq’s September 2026 Review and Outlook, the average U.S. benchmark declined 2.0%, while the median fell 2.7%. The Russell 2000 dropped 5.3%, showing how much weaker smaller-company stocks were than the large-cap technology-heavy indexes.
That difference is important because a relatively stable S&P 500 does not necessarily mean the broader stock market was equally strong.
Why September Was Different
The biggest feature of September was the gap between headline index performance and the performance of individual stocks.
Nasdaq reported that 83% of S&P 500 members were more than 10% below their respective 52-week highs, while 42% were more than 20% below those highs. At the same time, the Nasdaq-100 gained 3.3%, supported by large-cap growth companies in technology and communications.
The sector picture reinforced that divide. Technology gained about 4.5% and communications about 4.3%, while nine of the 11 major S&P 500 sectors declined during the month.
This created a market where index-level resilience depended heavily on a relatively narrow group of large companies.
Treasury Yields Became the Biggest Constraint
The bond market was one of the most important forces shaping September’s equity performance.
The 10-year Treasury yield rose 54 basis points during the month to 5.29%, while the 30-year yield reached 5.62%, according to Nasdaq’s September market review. Reuters also reported that September was one of the worst months for global bond markets in years, with the U.S. 10-year Treasury experiencing its largest monthly yield increase since 2022.
Higher long-term yields affect stocks through several channels.
First, they raise the discount rate used to value future corporate earnings. Growth companies whose valuations depend heavily on profits expected years in the future can therefore become more sensitive to changes in bond yields.
Second, higher Treasury yields increase borrowing costs across the economy. Businesses face more expensive financing, while households may encounter higher rates on mortgages, auto loans and other forms of credit.
Third, government bonds become more competitive with equities when their yields rise significantly.
Economic Reader’s explanation of How Interest Rates Affect the Economy provides more context on how changes in interest rates move through borrowing, spending, investment and financial markets.
The Fed Raised Rates, but the Bond Market Was the Bigger Story
The Federal Reserve raised the federal funds target range by 25 basis points at its September 15–16 meeting, bringing it to 3.75%–4.00%. The Federal Reserve’s September 16 FOMC statement said economic activity was expanding at a solid pace, domestic spending remained resilient, and inflation was still elevated.
The rate decision itself was important, but the larger market story was what happened to longer-term Treasury yields.
Short-term rates are heavily influenced by Fed policy expectations. Longer-term yields also reflect expectations for inflation, economic growth, government borrowing, debt supply and the compensation investors require for holding longer-duration bonds.
That distinction helps explain why equities could face pressure even while expectations for future Fed policy were changing.
Economic Reader’s Historical Fed Decisions provides additional context on how the central bank’s policy rate has changed over time.
Nasdaq Held Up While the Dow Fell
The different performances of the Nasdaq and Dow were partly a reflection of their different compositions.
Technology and communication companies benefited from continued enthusiasm around artificial intelligence, data centers, semiconductors and corporate technology spending. Large-cap growth therefore remained an important source of market support.
The Dow, by contrast, has a different sector composition and includes more mature industrial, financial, consumer and healthcare businesses. Those companies can respond differently to changes in borrowing costs, economic growth expectations and commodity prices.
September therefore showed that “the stock market” was not moving as one group. Investors were making increasingly selective decisions about which businesses could continue producing strong earnings in a higher-cost financial environment.
Oil and Inflation Complicated the Picture
Energy prices added another layer of uncertainty.
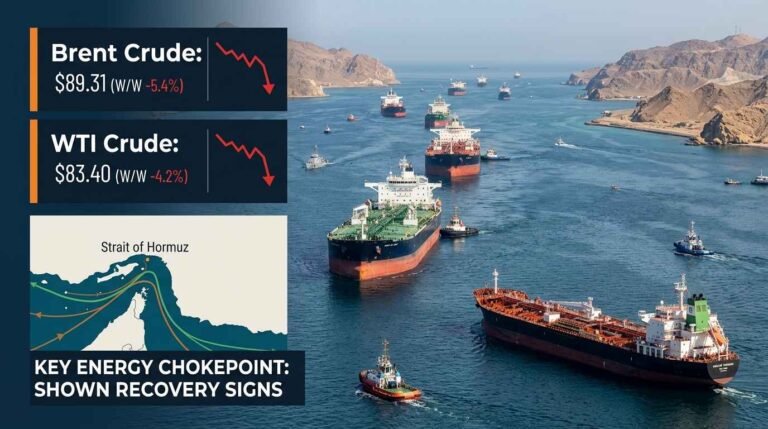
Brent crude gained about 14% during September, according to Reuters, as geopolitical tensions and tighter fuel supplies pushed oil prices higher.
U.S. inflation data also showed the importance of energy costs. The Bureau of Labor Statistics’ August 2026 CPI report showed headline CPI rising 3.4% over the year, while gasoline prices increased 3.9% during August. Energy prices were up 16.3% over the previous 12 months.
Higher oil prices can affect companies through transportation, manufacturing and input costs. They can also reduce household purchasing power when consumers spend more on gasoline and energy.
For investors, the concern was not simply higher oil prices themselves. The bigger issue was whether higher energy costs could keep inflation elevated and make it harder for monetary policy to become more accommodative.
Economic Data Sent Mixed Signals
September’s economic data did not provide a simple growth-or-inflation story.
The Bureau of Economic Analysis August Personal Income and Outlays report showed personal income rising 0.2% in August, while personal consumption expenditures increased 0.9%. Real PCE rose 0.6%.
At the same time, the PCE price index increased 3.4% from a year earlier, while core PCE increased 3.0%. The monthly PCE price index rose 0.3%, with core PCE up 0.2%.
That combination pointed to continued consumer activity alongside inflation that remained above the Federal Reserve’s 2% target.
For stocks, strong consumer spending can support corporate revenue and earnings. Persistent inflation, however, can keep interest rates higher for longer.
AI Remained a Major Source of Market Support
Artificial intelligence continued to play an unusually large role in September’s market leadership.
Technology companies remained supported by expectations for AI-related spending on semiconductors, computing infrastructure, data centers and software. The continued strength of large-cap technology helped the Nasdaq outperform broader parts of the market.
But the market’s growing dependence on AI-related earnings expectations also creates an important test for the next phase of the rally.
Investors will increasingly need evidence that large AI investments are translating into revenue growth, productivity gains and sustainable earnings rather than relying primarily on expectations of future demand.
Reuters reported that U.S. equity funds attracted $20.6 billion in net inflows during the week ending September 30, with AI optimism helping support investor demand despite concerns about Treasury yields. (Reuters)
What September Revealed About Market Leadership
September’s most useful lesson was about market breadth.
The S&P 500’s relatively modest 0.7% decline did not reflect equally strong performance across the market. Smaller companies performed much worse, while large-cap growth stocks provided substantial support.
That creates two different ways of looking at the market.
One is the index-level view: major benchmarks remained relatively resilient, particularly the Nasdaq.
The other is the breadth view: a large portion of individual stocks experienced significant declines.
The difference matters because broad participation can provide a stronger foundation for sustained market gains, while narrow leadership leaves the major indexes more dependent on a smaller group of companies.
What Investors Enter October Watching
Several variables will shape the U.S. stock market as the fourth quarter begins.
Treasury yields: Further increases could continue to pressure equity valuations, particularly long-duration growth stocks.
Corporate earnings: September’s technology leadership will face a stronger test as companies report whether AI-related investment is producing measurable financial returns.
Federal Reserve policy: The September rate increase moved the policy rate to 3.75%-4.00%. Investors will closely monitor inflation, employment and Fed communication for clues about the next policy decision. (Federal Reserve)
Labor-market data: A weakening labor market could change expectations for monetary policy, while a resilient labor market could give the Fed more flexibility to maintain higher rates.
Oil prices: Sustained energy prices above previous levels could put additional pressure on inflation and corporate margins.
Market breadth: Investors will be watching whether participation expands beyond large-cap technology and communications companies.
AI investment: Continued capital spending on AI infrastructure will remain an important driver of technology-sector expectations.
Where the U.S. Stock Market Stands Entering Q4
September did not produce a single market narrative. Instead, it highlighted a growing tension between two forces.
On one side, AI investment, strong technology earnings expectations and resilient consumer spending continued to support parts of the equity market.
On the other, higher Treasury yields, elevated inflation, expensive energy and tighter financial conditions created pressure on valuations and smaller companies.
That leaves the fourth quarter focused on a practical question: can corporate earnings broaden enough to support the wider market while long-term borrowing costs remain elevated?
The answer will depend on the interaction between earnings, inflation, Treasury yields, Federal Reserve policy and economic growth not on any single market indicator.