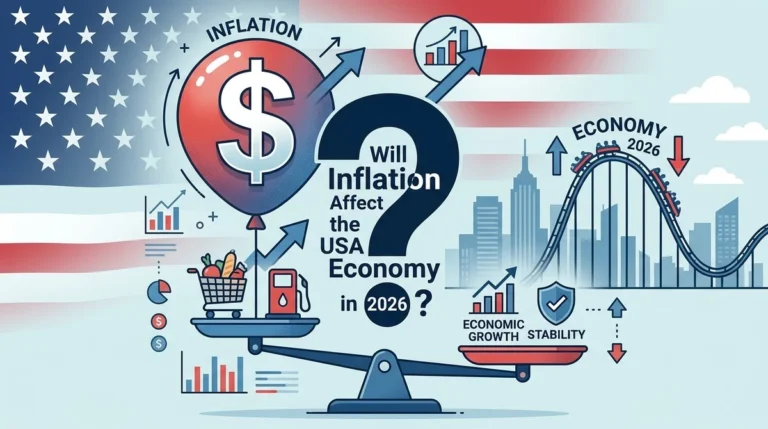
The U.S. Debt Problem: How Much Does the National Debt Really Matter?
U.S. Debt Problem: How Much Does the National Debt Matter?
The U.S. national debt is often discussed as if the headline number alone tells us whether the country has a debt problem.
It does not.
The more useful question is whether the federal government can continue financing its obligations without debt and interest costs rising faster than the economy can support them.
That requires looking beyond the size of the national debt and examining how debt interacts with economic growth, interest rates, budget deficits, Treasury issuance, and investor demand.
The Congressional Budget Office (CBO) projects that federal debt held by the public will equal about 101% of GDP in 2026 and rise to 120% by 2036 under its February 2026 baseline. It also projects federal deficits of $1.9 trillion in fiscal 2026 and $3.1 trillion in 2036. Net interest outlays are projected to rise from about $1.0 trillion in 2026 to $2.1 trillion in 2036. (Congressional Budget Office)
Those figures do not mean that the United States is about to default or that a debt crisis is inevitable.
They show why the mechanics of federal borrowing deserve closer attention.
The real issue is fiscal sustainability: whether debt can remain manageable relative to the size of the economy while the government continues financing its spending and interest obligations.
The National Debt Number Is Only the Starting Point
The U.S. government has accumulated a very large amount of debt, but the dollar amount by itself tells us relatively little.
A country with $10 trillion of debt could face very different circumstances depending on whether its economy produces $5 trillion or $30 trillion of output each year.
That is why economists often compare debt with GDP.
GDP provides a rough measure of the economic activity that generates household and business income, profits, and ultimately government tax revenue.
The more useful question is therefore not:
“How many dollars does the U.S. government owe?”
It is:
“How large are those obligations relative to the economy that supports them?”
That leads to debt-to-GDP.
Debt to GDP Shows the Direction of the Fiscal Burden
Debt-to-GDP compares government debt with the size of the economy.
If debt rises while GDP grows even faster, the ratio can fall.
If debt grows faster than GDP, the ratio rises.
This makes the direction of the ratio particularly important.
CBO’s February 2026 baseline projects federal debt held by the public at 101% of GDP in 2026 and 120% in 2036. Over the following two decades, its baseline shows the ratio reaching 175% of GDP by 2056. (Congressional Budget Office)
These are projections based on assumptions about current law and economic conditions, not guaranteed outcomes.
Still, the trajectory illustrates the central fiscal challenge: debt is projected to grow faster than the economy over an extended period.
The distinction between gross federal debt and debt held by the public also matters.
Gross federal debt includes debt held by outside investors as well as debt held by federal government accounts.
Debt held by the public focuses on Treasury securities owned outside the federal government and is particularly useful when considering how federal borrowing interacts with the broader economy.
Economic Reader’s The Rising U.S. National Debt: What It Means for Future Economic Growth and Taxes examines the broader consequences of the rising debt burden. This article takes a different approach by focusing on how debt becomes sustainable or increasingly difficult to finance.
The Fiscal Equation Starts with the Deficit
Debt is a stock.
The deficit is a flow.
That distinction explains how debt keeps accumulating.
When federal spending exceeds federal revenue, the government runs a budget deficit. It must then borrow to cover the difference.
CBO projects a federal deficit of approximately $1.9 trillion in fiscal 2026, equal to 5.8% of GDP. By 2036, the deficit is projected to reach $3.1 trillion, or 6.7% of GDP. (Congressional Budget Office)
The important issue is not one unusually large deficit.
Large deficits can occur during wars, recessions, financial crises, or other emergencies when governments deliberately borrow to support the economy or finance extraordinary spending.
The longer-term challenge is persistent deficits that continue outside those exceptional periods.
A simplified relationship is:
Budget deficit → new Treasury borrowing → higher outstanding debt
That process is manageable as long as the economy, government finances, and borrowing costs remain consistent with the debt path.
The difficulty increases when debt continues rising while interest costs begin taking up more of the federal budget.
Primary Deficits Reveal What Is Happening Before Interest
One of the most useful ways to examine fiscal sustainability is to separate the deficit into two parts.
The primary deficit excludes interest payments.
That helps answer a specific question:
Is the government adding to its debt because of current spending and revenue decisions, or mainly because of interest costs from previously accumulated debt?
CBO projects a primary deficit of 2.6% of GDP in 2026 and 2.1% in 2036. At the same time, net interest costs rise from 3.3% of GDP to 4.6%. (Congressional Budget Office)
This creates an important distinction.
A government can reduce its primary deficit while still seeing the total deficit remain large because interest payments are increasing.
The fiscal mechanics can therefore develop in stages:
Primary deficits → higher debt → higher interest expense → larger total deficits
That is one of the reasons the headline deficit can remain difficult to reduce even if the underlying spending-and-revenue gap improves somewhat.
The Interest Rate Growth Relationship
Debt sustainability depends heavily on two variables:
The interest rate paid on government debt
and
The rate at which the economy grows
Economists often summarize this relationship using r − g.
- r represents the effective interest rate on government debt.
- g represents nominal GDP growth.
Nominal GDP growth includes both real economic growth and changes in the overall price level.
If nominal economic growth is strong relative to the effective interest rate, debt can be easier to stabilize relative to GDP.
If the interest rate remains above nominal growth for a prolonged period, the government needs stronger primary fiscal performance to prevent debt from continuing to rise relative to the economy.
This does not mean a country automatically faces a crisis whenever r > g.
Debt dynamics also depend on the primary balance, the maturity of government debt, inflation, and other factors.
But the relationship provides a useful framework for understanding why growth matters so much to fiscal sustainability.
Economic Reader’s How Interest Rates Affect the Economy explains how interest rates influence borrowing, investment, financial markets, and economic activity more broadly.
Growth Can Help, but It Cannot Do All the Work
Economic growth increases the size of the economy against which debt is measured.
It can also increase household incomes, corporate profits, and tax revenues.
That makes stronger productivity and sustained economic growth valuable for fiscal sustainability.
But growth alone does not automatically solve a persistent deficit.
Suppose GDP grows rapidly while the government continues running large deficits that increase debt even faster.
The debt ratio can still rise.
The opposite is also possible. A period of strong nominal growth can temporarily make debt ratios easier to manage even while fiscal policy remains unchanged.
That is why growth should be viewed as one part of the debt equation rather than a substitute for sustainable budget policy.
Inflation Can Change the Arithmetic, but It Has Costs
Inflation affects debt dynamics in several ways.
Higher prices increase nominal GDP, which can make the debt-to-GDP ratio look better even when real economic growth is weak.
Inflation can also reduce the real value of existing fixed-rate government debt.
But persistent inflation can create another problem.
Investors may demand higher Treasury yields to compensate for the loss of purchasing power.
If those higher yields persist, the government eventually has to refinance some of its debt at higher rates.
That can increase future interest costs.
The result is a complicated trade-off:
Higher inflation → higher nominal GDP → potentially lower debt-to-GDP ratio
but also:
Higher inflation expectations → higher required yields → higher future borrowing costs
This is one reason governments cannot simply rely on inflation as a solution to a debt problem.
The Hidden Issue: Refinancing
A common misunderstanding is that a rise in Treasury yields immediately increases the interest cost on every dollar of existing federal debt.
It does not.
Treasury securities are issued with different maturities and interest rates.
A bond issued several years ago generally continues paying according to its original terms until maturity.
The government faces a higher borrowing cost when that debt needs to be refinanced and new securities are issued at higher market yields.
That creates a gradual transmission mechanism.
For example:
Treasury yields rise today → existing debt remains partly protected by its current rates → securities mature → Treasury refinances them → average borrowing costs gradually increase
This lag is important.
It means a government can experience a significant increase in market interest rates before the full effect appears in the federal interest bill.
CBO projects the average interest rate on debt held by the public to rise over its 2026–2036 projection period as older debt is refinanced. (Congressional Budget Office)
The refinancing schedule therefore matters almost as much as the headline Treasury yield.
Why a 5% Treasury Yield Matters to the Debt Outlook
The 10-year Treasury yield is one of the most visible market indicators of long-term borrowing costs.
It does not directly determine the average interest rate on all federal debt.
But it influences the rates at which new Treasury securities are issued and provides an important market signal about inflation, growth, monetary policy, and investor demand.
The key point for the debt discussion is simple:
Higher market yields eventually feed into higher refinancing costs.
The effect takes time, but if elevated yields persist long enough, the average interest rate paid on federal debt can rise.
That can make the fiscal equation increasingly difficult.
Who Buys U.S. Treasury Debt?
The U.S. government does not finance its deficits automatically.
Investors must be willing to purchase Treasury securities.
That makes Treasury demand an important part of the debt story.
Treasury securities are purchased by a wide range of investors, including banks, mutual funds, money-market funds, pension funds, insurance companies, households, foreign investors, and other institutions.
The Treasury publishes investor-class auction data showing how different categories of investors are allocated Treasury securities at auction. (U.S. Department of the Treasury)
Treasuries also serve several functions beyond simply providing a government investment.
They are used as highly liquid assets, collateral in financial markets, and reference points for pricing other forms of debt.
That broad demand helps support the enormous size of the Treasury market.
But strong demand does not mean unlimited demand at any price.
Investors care about the yield they receive.
Treasury Demand Is About Price, Not Just Participation
This is an important distinction.
A Treasury auction can attract plenty of buyers while still clearing at a higher yield.
That means the government can continue borrowing while the market simultaneously demands greater compensation for holding the debt.
The relevant question is therefore not simply:
“Did investors buy the Treasury securities?”
It is:
“What yield did investors require to buy them?”
Treasury’s auction system provides a direct market mechanism for answering that question. The department publishes auction announcements and results for marketable Treasury securities, allowing investors to examine issuance, yields, and other auction information. (U.S. Department of the Treasury)
This makes Treasury auctions one of the most useful real-time indicators for monitoring demand.
One weak auction does not establish a structural change.
A persistent pattern of weaker demand, higher required yields, or increasing difficulty absorbing large issuance would be more significant.
Foreign Investors Are Important, but They Are Not the Whole Story
Foreign ownership of Treasuries often receives disproportionate attention.
Foreign governments and investors are significant participants in the Treasury market, but they are only part of the investor base.
The Treasury’s International Capital system tracks cross-border portfolio investment and positions between U.S. and foreign residents. (U.S. Department of the Treasury)
Domestic investors also hold large quantities of Treasury securities.
This matters because the U.S. does not depend on a single foreign country to finance its debt.
Treasury demand is spread across a much broader financial system.
At the same time, foreign demand remains relevant because changes in overseas reserve management, exchange rates, global interest rates, and international portfolio allocation can affect Treasury markets.
The useful question is therefore not whether a particular foreign country is “funding America.”
It is whether total investor demand remains sufficient to absorb Treasury issuance at borrowing costs the government can sustain.
What Happens If Treasury Demand Weakens?
Suppose the Treasury needs to issue more debt while investors become less willing to hold additional securities at existing yields.
The market has a mechanism for adjusting.
Prices can fall and yields can rise until the securities offer a return that attracts sufficient demand.
That can create a chain reaction:
More Treasury supply + weaker demand → higher required yields → higher refinancing costs → higher interest expense
The effects can then spread into the wider economy.
Higher Treasury yields can influence corporate borrowing costs, mortgage rates, and the discount rates used to value financial assets.
That means fiscal pressure can eventually become a broader financial-conditions issue.
The Treasury market does not need to “collapse” for the debt burden to become more expensive.
A sustained increase in the cost of financing can be enough.
When Does High Debt Become a Market Problem?
There is no universal debt-to-GDP number at which every country suddenly becomes unsustainable.
Markets evaluate government debt in context.
Important factors include:
- The level and direction of debt-to-GDP
- Primary deficits
- Interest costs
- Economic growth
- Inflation expectations
- Average debt maturity
- Treasury demand
- Institutional credibility
- Currency status
- The government’s ability to adjust taxes or spending
The United States has several structural advantages.
The dollar plays a central role in global finance.
Treasury securities are widely used as liquid and relatively low-credit-risk assets.
The U.S. economy is large and diversified.
The Treasury market is deep and highly liquid.
These characteristics help explain why the United States can finance a very large debt market without facing the same constraints as a small country that borrows heavily in a foreign currency.
But those advantages do not eliminate fiscal arithmetic.
They provide financing capacity and flexibility, not unlimited borrowing capacity.
Debt Sustainability Is Different from Solvency
The U.S. government is not a household.
It issues debt in dollars, collects taxes in dollars, and operates within a monetary and financial system centered on the dollar.
That makes comparisons between federal debt and household credit cards misleading.
The relevant constraint is not simply whether the government has enough cash today to pay a bill.
It is whether the fiscal path can remain credible without creating increasingly damaging economic consequences.
A government can sustain debt for decades without paying it down to zero.
What matters is whether debt and interest obligations remain manageable relative to the economy.
That is why fiscal sustainability is a more useful concept than asking whether the United States can simply “run out of money.”
What Could Push the Debt Problem into a More Difficult Phase?
Several forces could make the fiscal path harder to manage.
Persistent Primary Deficits
If spending continues to exceed revenues even before interest payments are counted, new debt keeps accumulating.
Higher-for-Longer Interest Rates
If market yields remain elevated, more maturing debt will eventually be refinanced at higher rates.
Slower Nominal GDP Growth
If nominal GDP growth weakens, the economy may have less capacity to absorb a growing debt burden.
Faster Treasury Issuance
Large deficits require continued borrowing.
If issuance expands faster than investor demand, higher yields may be required.
Rising Inflation Expectations
Investors may demand greater yields when they expect inflation to remain elevated.
Weaker Fiscal Credibility
If investors become less confident that future policymakers will eventually stabilize debt, they may require additional compensation for holding longer-term Treasuries.
These forces can reinforce one another.
For example:
Large deficits → more Treasury issuance → higher yields → higher interest costs → larger deficits
That feedback loop is more important than any single year’s debt number.
What Could Keep the Debt Manageable?
The same system can move in the other direction.
Stronger Productivity and Economic Growth
A larger economy increases the tax base and makes a given amount of debt smaller relative to GDP.
Lower Borrowing Costs
Lower average interest rates reduce the cost of refinancing maturing debt.
Smaller Primary Deficits
Reducing the gap between government revenues and noninterest spending slows the accumulation of new debt.
Continued Treasury Demand
A broad investor base can help the government finance large amounts of debt without requiring an extreme increase in yields.
Credible Long-Term Fiscal Policy
If investors believe policymakers can eventually respond to rising debt, confidence in Treasury securities can remain strong.
No single factor determines the outcome.
Fiscal sustainability comes from the interaction of growth, interest rates, deficits, revenues, spending, and investor demand.
What Should Investors Watch?
The national debt changes slowly, but the market signals surrounding it can change much faster.
Several indicators deserve attention.
Debt-to-GDP
The direction of the ratio matters more than a single annual number.
A stable ratio and a rapidly rising ratio imply different fiscal conditions.
Primary Deficit
This shows whether the government is adding to debt through current spending and revenue decisions before interest costs are included.
Net Interest Costs
Interest expense shows how much of the federal budget is being absorbed by previously accumulated debt.
CBO projects net interest outlays to rise from about $1.0 trillion in 2026 to $2.1 trillion in 2036. (Congressional Budget Office)
Treasury Yields
Long-term yields provide information about the market’s required return for holding U.S. government debt.
A sustained increase can eventually raise refinancing costs.
Treasury Auction Results
Auction yields and investor participation can provide information about demand for newly issued debt.
Treasury’s official auction data are available through its marketable securities and investor-allotment databases. (U.S. Department of the Treasury)
Nominal GDP Growth
The combination of real growth and inflation affects the denominator of the debt-to-GDP ratio.
The Yield Curve
The relationship between short-, medium-, and long-term Treasury yields can provide additional information about expectations for monetary policy, inflation, and economic growth.
Three Broad Paths for the U.S. Debt Outlook
The future does not have to follow one predetermined path.
A Gradual Fiscal Adjustment
Future policymakers could reduce primary deficits through some combination of revenue increases, spending changes, or reforms.
Debt could continue rising for a period before stabilizing relative to GDP.
Stronger Economic Growth
Higher productivity and stronger nominal growth could improve the debt-to-GDP trajectory and increase tax revenues.
This would make the existing debt burden easier to support, although growth alone may not eliminate persistent deficits.
Continued Fiscal Pressure
If large primary deficits persist while interest rates remain elevated, interest costs could consume a growing share of federal resources.
The government could then face increasing pressure to adjust spending, revenues, or borrowing.
These scenarios are not mutually exclusive.
The actual fiscal path will depend on economic growth, interest rates, inflation, fiscal policy, and future investor demand.
What the National Debt Does Not Tell You
A large debt-to-GDP ratio does not automatically mean that:
- The U.S. is about to default.
- Treasury securities will suddenly become unattractive.
- Inflation must accelerate.
- Interest rates must rise every year.
- Foreign investors will stop buying Treasuries.
- Economic growth must collapse.
- Taxes must immediately increase.
Those conclusions require additional evidence.
The debt number becomes more informative when combined with the variables that determine how it is financed.
That is why investors and economists monitor debt, deficits, interest costs, growth, Treasury yields, and investor demand together.
The Real Test of U.S. Fiscal Sustainability
The U.S. debt problem is not simply a story about a very large number.
It is a story about the interaction between government borrowing and the financial system that supports it.
The key relationships can be summarized as:
Deficits → new borrowing → higher debt
Higher debt → greater refinancing needs
Higher refinancing needs + higher yields → rising interest costs
Rising interest costs → greater pressure on future deficits
At the same time:
Economic growth → larger GDP and tax base → greater capacity to support debt
And:
Strong Treasury demand → easier financing at lower required yields
That is the framework that makes the national debt easier to understand.
The United States has significant advantages: a large economy, a deep Treasury market, a globally important currency, and a broad investor base.
Those strengths give the government substantial financing capacity.
But financing capacity is not the same thing as unlimited fiscal space.
CBO’s current baseline illustrates why the long-term trajectory deserves attention. Debt held by the public is projected to rise from 101% of GDP in 2026 to 120% in 2036, while net interest costs more than double from $1.0 trillion to $2.1 trillion over the same period. (Congressional Budget Office)
Those projections can change.
Economic growth can be stronger or weaker than expected. Interest rates can move. Fiscal policy can change. Treasury demand can evolve.
The central issue is therefore not whether the U.S. should have zero debt.
Modern governments can operate with substantial debt for long periods.
The more important question is whether debt, deficits, interest costs, and economic growth remain on a path that investors and the federal budget can continue to support.
That is ultimately how much the national debt really matters.